Annual Financial Audit
Enhance your financial credibility with accurate and transparent annual audit services.
T
Admin
August 21, 2026
Annual financial statements are more than documents prepared for government filing. They communicate a company’s financial position, operating performance, cash flow and readiness for future growth.
Incomplete accounting records, incorrect cut-off procedures or insufficient supporting documents can affect the auditor’s report, statutory filing, tax calculations and the confidence of shareholders, banks, investors and business partners.
Taxpoint’s annual financial statement audit service helps businesses organize their information, address important issues before statutory deadlines and coordinate efficiently among management, accounting personnel and the auditor.
What is an annual financial statement audit?
An annual financial statement audit is a process in which an auditor obtains and evaluates evidence to form an opinion on whether the financial statements have been prepared in accordance with the applicable financial reporting framework and are free from material misstatement.
The auditor applies professional judgment, assesses risk and performs appropriate tests. An audit therefore provides reasonable assurance rather than absolute assurance. It does not examine every transaction and cannot guarantee that every error or instance of fraud will be detected.
Management remains responsible for preparing the financial statements, selecting appropriate accounting policies and maintaining suitable internal controls. The auditor’s responsibility is to examine the evidence and express an independent opinion.
Which businesses require an audit?
The qualified person who may sign the report depends on the type and size of the entity.
Thai limited companies and other entities specified by law generally require their financial statements to be audited by a Thai Certified Public Accountant, or CPA.
A small Thai registered partnership with capital not exceeding THB 5 million, total assets not exceeding THB 30 million and total revenue not exceeding THB 30 million may qualify for an exemption from a CPA audit. Its accounts may be examined and certified by a Tax Auditor, or TA, within the scope permitted by the Revenue Department.
A TA is not permitted to certify the dissolution-period financial statements of a qualifying partnership that has registered its dissolution.
Regulated entities, groups of companies and businesses subject to lender, investor or parent-company requirements may need additional procedures or reporting.
The entity’s legal form and current financial information should be reviewed before appointing an auditor.
Important filing deadlines
A Thai registered partnership must generally submit its annual financial statements within five months of the end of its accounting period.
A limited company must hold an annual general meeting to approve its financial statements within four months of the accounting period end and submit the approved statements to the Department of Business Development within one month of the approval date.
Financial statements are generally submitted through DBD e-Filing. The exact date depends on the accounting period end, entity type and any current government announcements, so businesses should confirm their applicable deadline each year.
What does the auditor examine?
The audit scope depends on the business, assessed risks, materiality and available evidence. Important areas may include:
Cash, bank balances and bank reconciliations
Revenue, trade receivables, collections and revenue cut-off
Purchases, expenses, trade payables and payments
Inventory, product costs, stock movements and count results
Property, plant and equipment, fixed-asset records and depreciation
Borrowings, interest, commitments and related-party transactions
Payroll, employee benefits, withholding tax and social security records
Value added tax, corporate income tax and related tax accounts
Accounting estimates, impairment and going-concern considerations
Financial statement presentation and note disclosures
Our annual audit process
1. Understanding the business and agreeing on the engagement
The auditor studies the company’s operations, revenue model, accounting system, reporting period and significant issues. Independence and acceptance requirements are considered before an engagement letter is issued.
2. Planning and risk assessment
Areas that could contain material misstatements are identified. The auditor also obtains an understanding of the relevant business processes and internal controls.
3. Preparing the information request
A prepared-by-client list, commonly called a PBC List, is provided so the accounting team can organize the required records and reduce repeated requests.
4. Testing transactions and obtaining evidence
The auditor examines supporting documents, tests selected transactions, reviews account reconciliations and cut-off procedures, and may request external confirmations from banks, customers, suppliers or other parties.
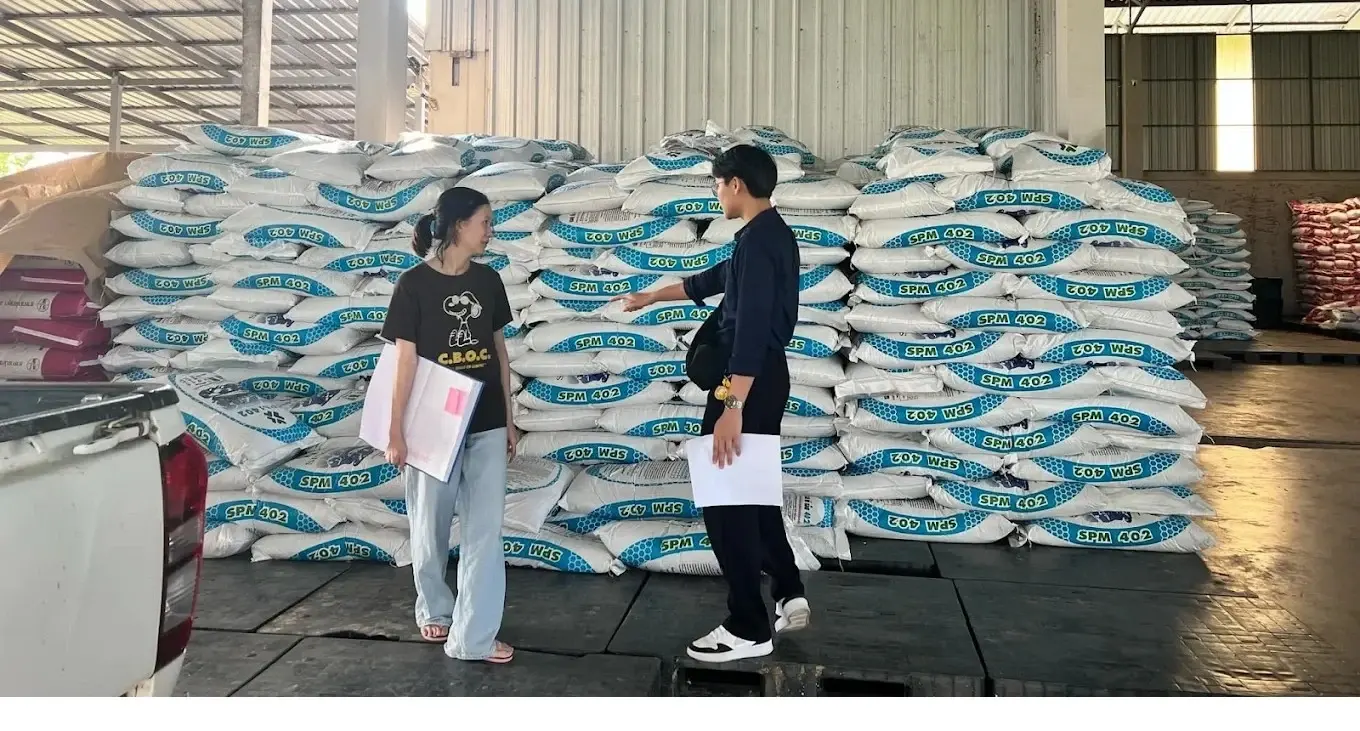
5. Observing inventory
When inventory is material to the financial statements, the auditor may attend the physical count, observe inventory-control procedures and perform test counts.
6. Discussing findings and proposed adjustments
Where information is inconsistent, evidence is incomplete or an accounting adjustment may be required, the auditor discusses the matter with management and the accounting team before the financial statements are finalized.
7. Completing the audit and issuing the report
After sufficient appropriate evidence has been obtained, the auditor evaluates the financial statements as a whole and issues a report based on the findings and applicable professional standards.
Understanding the auditor’s opinion
An audit report is not simply a pass-or-fail result. Depending on the evidence and circumstances, the opinion may be:
An unmodified opinion when the financial statements are fairly presented in all material respects
A qualified opinion when a material matter exists but is not pervasive to the financial statements
An adverse opinion when a material misstatement is also pervasive
A disclaimer of opinion when sufficient appropriate evidence cannot be obtained and the possible effects could be both material and pervasive
Starting early gives management time to provide explanations, obtain missing evidence and consider necessary adjustments before the filing deadline.
Documents commonly required
The exact request depends on the size and complexity of the business. Common documents include:
Trial balance, general ledger and draft financial statements
Journals and detailed account schedules
Bank statements and bank reconciliations
Accounts receivable, accounts payable, accrued income and accrued expense schedules
Tax invoices, receipts, contracts and payment documentation
Inventory records and physical count documents
Fixed-asset register and depreciation schedules
Monthly tax returns, corporate income tax records and social security information
Company affidavit, shareholder information, meeting minutes and material agreements
Prior-year financial statements and auditor’s report
Records supporting transactions with directors, shareholders and related parties
Business benefits of a quality audit
An effective annual audit can help a business:
Meet its legal obligations and prepare for statutory filing
Improve the credibility of financial information
Identify inconsistencies in records and supporting documents earlier
Strengthen internal controls and document-management procedures
Use more reliable information for planning and decision-making
Reduce last-minute pressure before filing deadlines
Prepare for loan applications, investment or business expansion
Audit recommendations do not eliminate all business risks. Management must continue to maintain an effective accounting system and suitable internal controls.
Taxpoint’s service scope
Assessing the entity type and recommending an appropriately qualified auditor
Planning the audit according to the business and assessed risks
Conducting the annual audit through a CPA or TA within the legally permitted scope
Coordinating with management and the accounting team
Communicating identified issues and proposed adjustments
Issuing the auditor’s report based on professional standards and audit findings
Providing practical observations on documentation and internal controls identified during the engagement
DBD e-Filing, tax-return filing and services outside the financial statement audit should be clearly stated in the engagement scope and quotation before work begins.
Prepare early and avoid unnecessary year-end pressure
Do not wait until the filing deadline is approaching before collecting documents. Early preparation provides time to investigate unusual balances, obtain external evidence and correct accounting information where appropriate.
Taxpoint can assess the engagement, provide a document checklist and plan an annual financial statement audit that suits your business.
Contact us for a free initial consultation before making a decision. Build confidence in your financial statements and prepare your business for timely statutory reporting.