Thailand P.N.D.51 2026: Profit Estimate and Deadlines
Prepare Thailand's 2026 P.N.D.51 with a supportable taxable-profit estimate, key deadlines and an organized filing record.
50 views
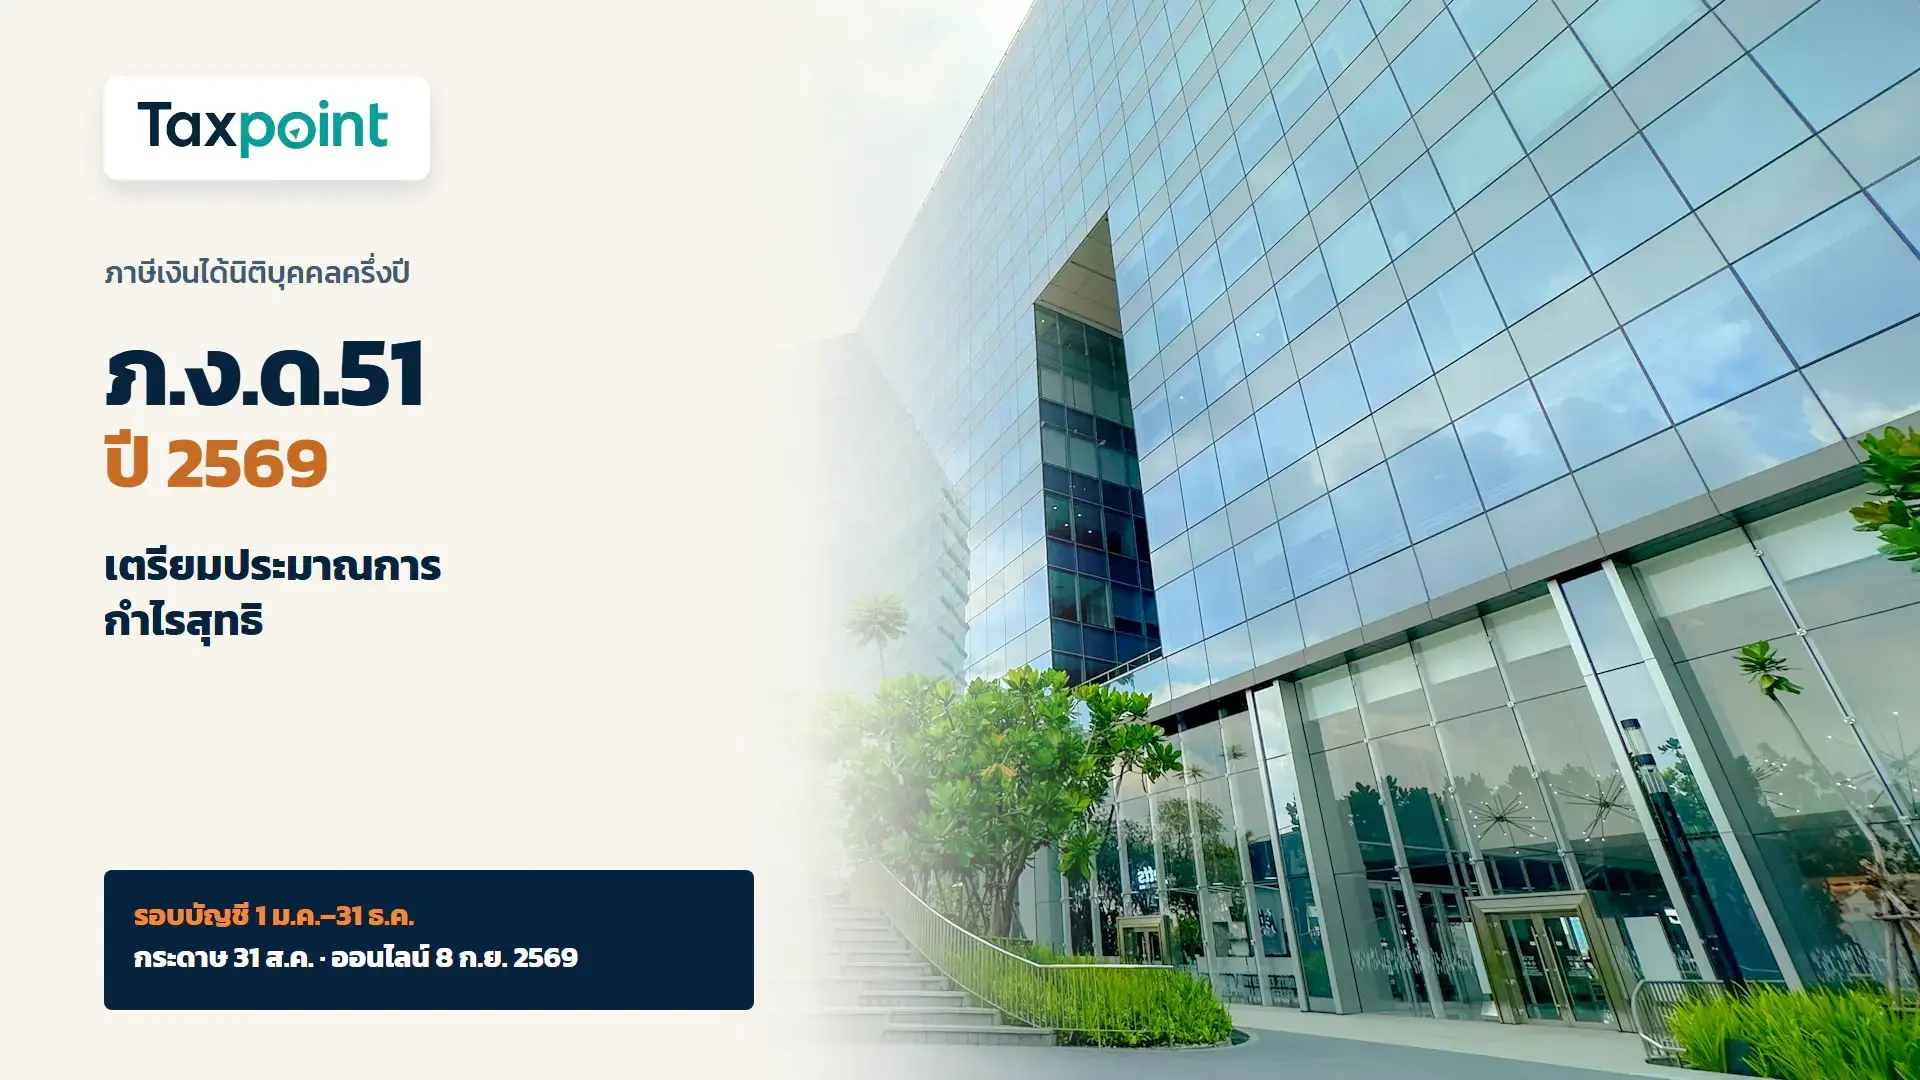
Businesses in Chiang Rai and elsewhere in Thailand that operate as companies or juristic partnerships should review their P.N.D.51 duty before the annual accounts are closed. For an accounting period from 1 January to 31 December 2026, the Revenue Department's national tax calendar sets the paper filing deadline at 31 August 2026 and the online filing deadline at 8 September 2026.
The difficult part is not merely completing the form. A business must support its tax-profit estimate, reconcile accounting profit to taxable profit, and determine whether it belongs under the full-year estimation method or the actual first-six-month profit method. This article provides a review framework; it is not a ruling on any particular taxpayer's facts.
What is P.N.D.51?
P.N.D.51 is the corporate income tax return under Section 67 bis of Thailand's Revenue Code for the half-year accounting period. The Revenue Department has published the 2026 form and filing instructions.
For most businesses, the half-year payment is an advance corporate income tax payment rather than the final annual settlement. The company must still calculate and file its annual corporate income tax return using actual full-year information. The Revenue Department states that overpaid P.N.D.51 tax may be claimed as a refund or used as a credit in the year-end calculation, subject to the applicable rules.
Entities in scope and exceptions to review
As a general rule, a company or juristic partnership with an accounting period of at least 12 months should review its P.N.D.51 filing duty. The Revenue Department divides filers into two broad calculation groups: businesses that estimate their full-year taxable profit or loss, and specified businesses taxed on actual taxable profit for the first six months.
Common distinctions include the following:
A first accounting period shorter than 12 months does not require a P.N.D.51 return, according to the Revenue Department's FAQ.
Foundations and associations do not file this return because their income tax basis does not require an estimated taxable profit or loss.
A joint venture is treated as a company or juristic partnership under the Revenue Code and must file.
Individuals do not use P.N.D.51 because this form is for juristic entities.
P.N.D.51 deadlines for 2026
For a juristic entity whose accounting period begins on 1 January and ends on 31 December, the Revenue Department confirms these dates:
Filing channelDeadlinePaper filing31 August 2026Online filing8 September 2026
These dates apply only to calendar-year accounting periods. A business with a different accounting year must calculate its deadline from the last day of the first six-month period. The underlying online-filing rule states two months from that date, while the Revenue Department has specifically confirmed 8 September 2026 for the 2026 calendar-year online filing. A business using another accounting period should therefore check the calendar or announcement applicable to its own period.
P.N.D.51 has two main calculation cases
Before entering figures, identify the method applicable to the business because the supporting information and filing requirements differ.
Estimated full-year taxable-profit method
Most companies and juristic partnerships estimate the taxable profit or loss expected for the entire accounting period and calculate their half-year tax from one-half of that estimated taxable profit under the rules applicable to the business. The process must start from taxable profit, not unadjusted accounting profit.
A traceable approach is to forecast full-year revenue, separate costs and expenses by period, adjust the accounting figures under the tax rules, and document assumptions such as signed contracts, order backlog, seasonality and committed expenditure.
Actual taxable profit for the first six months
Listed companies, commercial banks, certain regulated financial businesses and other entities meeting Revenue Department conditions use actual taxable profit for the first six months. This method may require the name of the auditor or tax auditor and the attachment of financial statements and a certification letter under the relevant rules. A business should not select the method solely from the form name or last year's practice without checking its current status.
How to build a supportable estimate
A sound estimate is not a guess intended to resemble last year's tax. It connects first-half records with evidence-based expectations for the second half.
Close the first six months' revenue and cost records, including accruals and documents not yet posted.
Separate tax adjustments, including non-deductible expenses, conditionally deductible items and exempt income.
Forecast the second half using orders, contracts, budgets and supported seasonal patterns.
Compare the forecast with prior-year actuals and the approved budget, and explain material differences.
Retain the calculation version, preparer, approver and supporting evidence as one review file.
Risk when taxable profit is materially underestimated
The Revenue Department explains that if estimated taxable profit is more than 25% below actual taxable profit without reasonable cause, a surcharge of 20% of the tax shortfall may apply. The assessment involves more than the numerical difference; reasonable cause, the timing of correction and the business's facts also matter.
To manage the risk, retain evidence showing what information was available when the estimate was prepared and review events that changed afterward. If an error is found, do not wait until year-end. Ask the accountant or tax adviser to determine whether an additional return is needed and how any surcharge applies to the actual circumstances.
Records and information to prepare
Although a branch-office paper filing generally does not require attachments and withholding tax certificates do not need to accompany the return, the business should retain auditable records. A useful preparation file includes:
the first-six-month trial balance and general-ledger details;
revenue, cost and expense reports, including accruals;
the reconciliation from accounting profit to taxable profit;
the second-half forecast and evidence supporting its assumptions;
withholding tax certificates for reconciliation, although they are not attached to the return;
the P.N.D.51 return, submission evidence, payment receipt and reference number; and
financial statements and the auditor or tax auditor's certification, if the business is in the actual-first-six-month-profit group.
Online filing, payment and corrections
If an online return has tax payable, the Revenue Department requires electronic payment together with the filing. The process must therefore be completed by the deadline. Do not stop after submitting the data: confirm the payment status, download the receipt and retain the filing evidence.
If the return contains incorrect information, the Revenue Department's FAQ directs the taxpayer to file an additional return with complete and correct figures. A late return may be subject to a fine of up to THB 2,000, and tax payable may attract a statutory surcharge. The actual amount depends on the filing and payment dates, written notices received and the facts of the case, so confirm the amount with the relevant Revenue Branch Office or a qualified adviser before payment.
How Tax Point can help prepare P.N.D.51
Tax Point Accounting can help review the accounting period and filing duty, reconcile the first six months, prepare a tax-adjustment schedule, test second-half assumptions and organize the filing information supported by the business's records. The service helps establish a review process based on the available facts; it does not guarantee a tax amount, audit outcome or acceptance by a government authority. (Tax Filing)
If you are unsure whether the estimation or actual-profit method applies, or whether a special item changes taxable profit, you can arrange an initial discussion with Tax Point to identify the records that require further review. (Contact Us) (รับทำบัญชี วางแผนภาษี วางระบบบัญชีและสอบบัญชี เชียงราย by TaxPoint)
Final pre-filing checklist
Confirm the accounting period and P.N.D.51 filing duty.
Use the calculation method applicable to the entity.
Reconcile accounting profit to taxable profit.
Document the full-year forecast assumptions and supporting evidence.
Review the risk of estimating taxable profit more than 25% below actual taxable profit.
For a 1 January–31 December period, file on paper by 31 August 2026 or online by 8 September 2026.
Complete payment and retain the return, receipt and reference number.
The filing deadline information in this article has been verified as of August 10, 2026, and applies only to businesses with an accounting period from January 1 to December 31.
Before publication, the Revenue Department links should be tested, the current status of the e-Filing system should be checked, and the wording regarding surcharges, reasonable cause, calculation methods, and documentation requirements specific to each type of business should be reviewed again by a qualified tax professional.
P.N.D.94 for Tax Year 2026: Must Freelancers, Online Sellers and Business Owners File by 30 September?68 views